Every finance influencer tells you SIP is the best way to invest. They're half right. SIP isn't mathematically optimal, it's emotionally optimal. And for 95% of people, emotional optimisation matters more than mathematical optimisation.
What the data actually says
Backtests on Indian large-cap indices since 2000 show that lumpsum-on-day-1 beats a 12-month SIP roughly 65% of the time. But the years lumpsum loses, it loses badly (2000, 2008, 2020). SIP is the better insurance against entering at a market peak.
The step-up SIP is the secret weapon
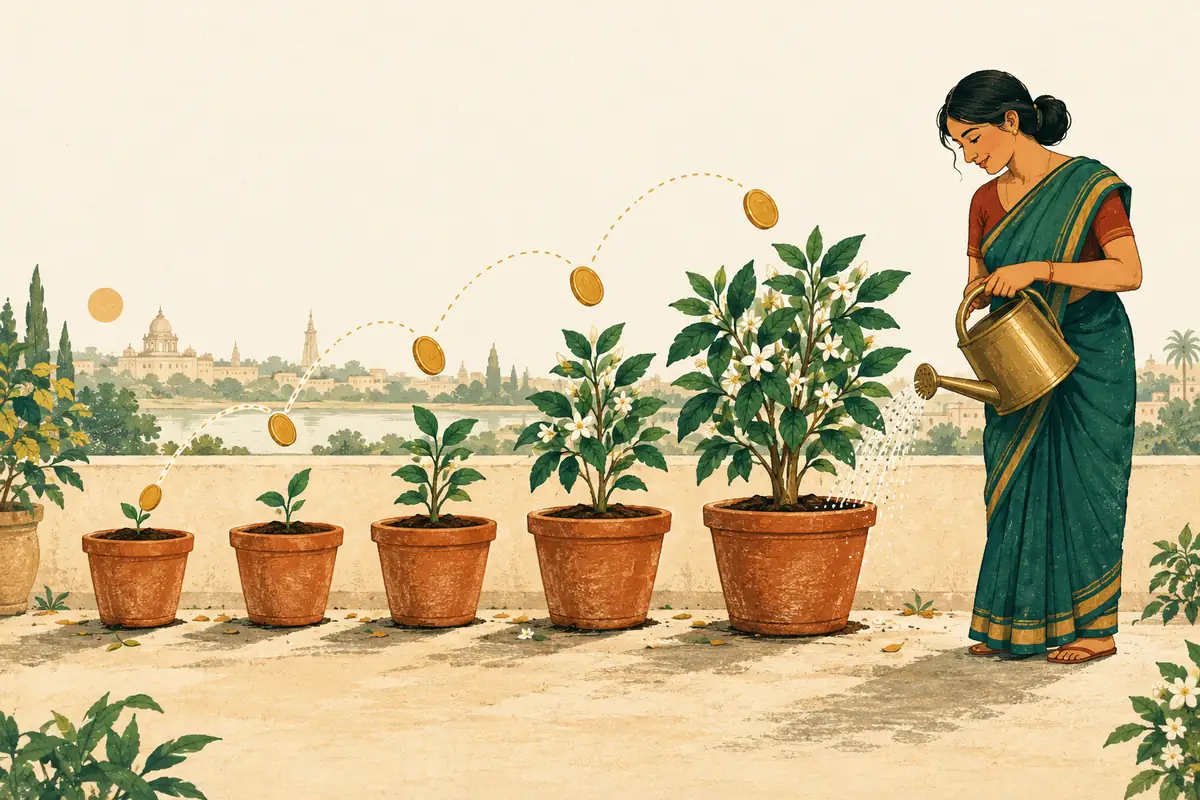
A flat ₹10,000/month SIP for 20 years at 12% gives you about ₹99 lakh. A ₹10,000/month SIP with a 10% annual step-up at the same rate gives you about ₹1.8 crore. Same starting point, near-double outcome.
What to do next
- Pick one broad-market index fund and one mid/small-cap fund.
- Set a SIP at 30% of your current monthly investible surplus.
- Set annual step-up to 10% (every March, contributions increase 10%).
- Don't check the value more than once a quarter.
Put this article to work
SIP CalculatorMonthly SIP with step-up, future value, real return.Open calculator →First Crore CalculatorWhen will your SIP hit your first ₹1 crore? And why the 2nd is faster.Open calculator →The Cost of WaitingWhat each year of delaying your SIP quietly costs you by retirement.Open calculator →What's That Daily Habit Costing You?Coffee, Swiggy, OTT, see what they really cost over 10 years.Open calculator →