Most people do not have a budget, they have a vague hope that money will be left over at the end of the month. It rarely is, because spending expands to fill whatever arrives. A budget rule fixes this by deciding the split in advance, so saving happens first and spending lives within what remains. The popular 50-30-20 rule is a fine idea imported badly, because it was built for incomes where EMIs are smaller and savings culture is different. Here is a version tuned for India.
The 50-30-15-5 split
| Share | Bucket | What goes in it |
|---|---|---|
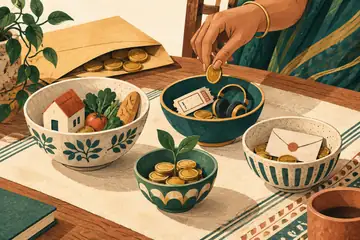
| 50 percent | Needs | Rent or home EMI, utilities, groceries, transport, school fees, insurance premiums |
| 30 percent | Wants | Eating out, subscriptions, travel, shopping, the discretionary life |
| 15 percent | Investing | SIPs, PPF, NPS, the money that builds your future |
| 5 percent | Buffer or extra debt | Top up the emergency fund, or prepay high-interest debt |
Notice that the investing bucket is carved out explicitly, before the wants. That is the whole trick. When you start a SIP on the day your salary lands, the 15 percent is invested before you can spend it, and you build your life around the rest. Do it the other way round, spend first and invest the remainder, and the remainder is almost always zero.
How to actually use it
- Anchor on take-home pay, the amount that actually hits your account, not your gross CTC.
- Automate the 15 percent first. Set the SIP and any recurring investment to auto-debit two days after payday, so it leaves before the spending starts.
- Use the 5 percent buffer to build your emergency fund until it is full, then redirect it to extra investing or clearing high-interest debt.
- Tighten the 30 percent wants bucket first when money is tight, starting with the subscriptions you forgot about. The needs bucket is much harder to cut quickly.
Frequently asked
What to do next
- Find your real monthly take-home pay, then split it into needs, wants, investing and buffer.
- Run your numbers through the budget analyser to see how your actual spending compares with 50-30-15-5.
- Automate the investing bucket first, with a SIP that auto-debits two days after payday.
- If needs are over 50 percent, protect a small investing bucket anyway and work on the big costs over time.